Last November, Kaseya Center hosted America Business Forum, a two-day gathering of presidents, CEOs, athletes, and investors that Miami used to sell itself as a world city. You did not need a ticket

Dated: August 21 2026
Views: 36
Why waiting for rates to drop may not be your only option
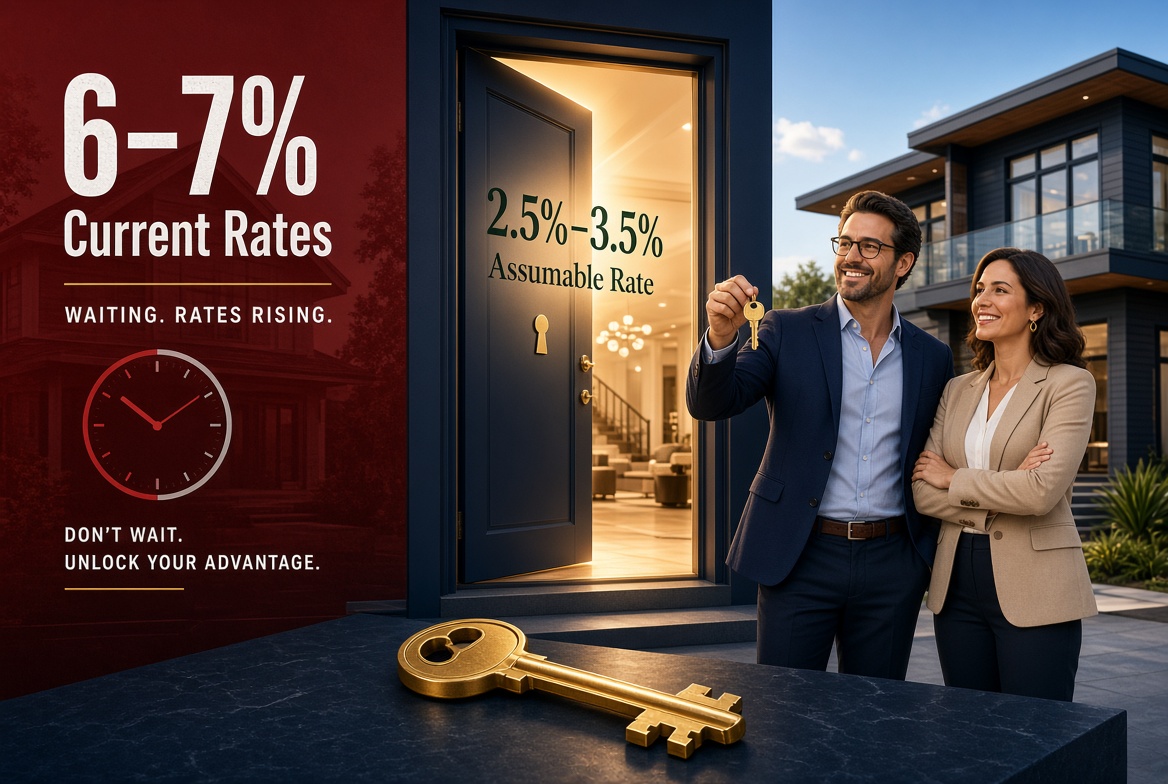
There’s a quiet frustration a lot of buyers are feeling right now. You’re ready to buy, but mortgage rates are still sitting in the 6–7% range. Every month you wait for rates to drop feels like money left on the table. Here’s what most buyers don’t realize:
You may not have to wait.
Assumable mortgages allow you to take over a seller’s existing loan, including their original interest rate. Many of these loans still carry rates between:
2.5% – 3.5%
That’s not a refinance. That’s not a special bank program. It’s simply taking over the loan that’s already on the house. These opportunities are often overlooked by listing agents, and a meaningful number of them are even off-market.
This has become one of the smartest ways to buy a home without waiting for the Fed to cut rates.
When you assume a mortgage, you step into the seller’s existing loan. That means:
On a $350,000 loan balance, the difference between a 3.5% rate and a 7% rate can easily exceed $700 per month. Over time, that adds up fast.
And here’s the part most buyers miss: FHA, VA, and USDA loans are generally assumable. In many cases, even non-veterans can assume a VA loan.
“These deals take 4–6 months” → Most close in 45–60 days
“Only veterans can assume VA loans” → Anyone can assume them
“The seller stays liable” → The seller receives a full release of liability
“The cash gap makes it impossible” → There are specific strategies (including Primary + Secondary financing) that solve this
These low-rate loans were originated during the 2020–2022 period. As more buyers discover this strategy, competition for these properties will increase. The window to take advantage of these rates is open right now, but it won’t stay wide open indefinitely.
Most agents still aren’t talking about this. Most buyers still don’t know it exists. That’s exactly why the people who act on this early will have a real advantage.
If you’re actively looking to buy (or thinking about selling a home that has a low-rate assumable loan), this is something you should explore before more people catch on.
I can help you:
If you’d like to see whether this could work for you, call me at (561) 556-4765. These rates already exist. The only question is whether you’ll use them.
Looking forward to hearing from you.
These low-rate opportunities won’t stay under the radar forever.
As more buyers learn about them, the advantage starts to disappear.
See If This Strategy Works for You
🔹 Luxury Real Estate Advisor | Data-Driven Negotiator | Crypto-Friendly CloserI’m Marcel, GRI, a luxury real estate advisor in South Florida specializing in new construction, off-market oppor....
Last November, Kaseya Center hosted America Business Forum, a two-day gathering of presidents, CEOs, athletes, and investors that Miami used to sell itself as a world city. You did not need a ticket
Why waiting for rates to drop may not be your only optionThere’s a quiet frustration a lot of buyers are feeling right now. You’re ready to buy, but mortgage rates are still sitting in
Brickell Key · MiamiA complete guide to every residential tower on the island — history, unit mixes, policies, and how the existing inventory compares to the upcoming Mandarin Oriental
Are you dreaming of sunny beaches, vibrant communities, and stunning landscapes?Throughout this Best Places to Live in Palm Beach County | Unveiling My Favorite 10 Destinations blog series, we
 Copyright Southeast Florida Multiple Listing Service © 2026. Accuracy of listing information is not guaranteed. Listing information is provided for personal consumer, non-commercial use, solely to identify potential properties for potential purchase. All other use is strictly prohibited, is a violation of the terms of use, and may violate federal and state law.
Data Last Updated: September 25, 2026 11:00 AM UTC
 IDX information is provided exclusively for consumer's personal, non-commercial use. Data may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Data is deemed reliable but not guaranteed.
The Tallahassee Board of REALTORS® Inc Data on this site was last updated: September 25, 2026 10:51 AM UTC
 All information regarding a property for sale, rental or financing, school information and public tax records is from sources deemed reliable; PROVIDED, HOWEVER, that representations and warranties are not made about the accuracy thereof, and such information is subject to errors, omissions, updates, modifications, changes of price, rent rates, commissions, prior sales, leases or financing, changes in school boundaries, or withdrawal without notice. All information displayed on this Website should
be independently verified if any person intends to engage in a transaction based upon such information.
Show More...
 © 2026 Florida Gulf Coast MLS (FGCMLS) Information deemed reliable, but not guaranteed. The IDX data relating to real estate for sale on this web site comes in part from the Florida Gulf Coast Multiple Listing Service. The information being provided is for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but not guaranteed.
 This data is up-to-date as of September 25, 2026 11:02 AM UTC Some properties that appear for sale on this website may subsequently have sold and may no longer be available. For the most current information, contact eXp Realty in Palm Beach Florida and Greater Fort Lauderdale.
The information provided is for consumers' personal, non-commercial use and may not be used for any other purpose. The data relating to real estate for sale on this website comes in part from the Broker Reciprocity Program
(BR Program) of M.L.S. of Naples, Inc., Florida Gulf Coast MLS, Marco Multi-List, Inc., My Florida Regional MLS, or Miami Association of Realtors. Properties listed with brokerage firms other than eXp Realty in Palm Beach Florida and Greater Fort Lauderdale are marked with the BR Program Icon or the BR House Icon and detailed information about them includes the name of the listing brokers. The properties displayed may not be all the properties available through the BR Program. The data provided by the Broker Reciprocity Program, and the Information is Deemed Reliable But Not Guaranteed. The source of the information about real property available for sale or rent is the copyrighted and proprietary database of the M.L.S. of Naples, Inc., Florida Gulf Coast MLS, Marco Multi-List, Inc., My Florida Regional MLS, or Miami Association of Realtors. Copyright 2026 M.L.S. of Naples, Inc., Florida Gulf Coast MLS, Marco Multi-List, Inc., My Florida Regional MLS, Miami Association of Realtors.; all rights reserved.
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than eXp Realty in Palm Beach Florida and Greater Fort Lauderdale may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 25, 2026 10:31 AM UTC
Show More...
